Medicare Supplement Plans A Through N Explained
 Medicare Supplement Plans A Through N help cover many of the out-of-pocket costs that Original Medicare does not pay. Understanding Medicare Supplement Plans A Through N can feel overwhelming because each plan offers different levels of coverage. Many people approaching Medicare ask the same question: “What do all the Medicare Supplement Plan letters mean?”
Medicare Supplement insurance, also known as Medigap, helps pay some of the costs that Original Medicare leaves behind, including certain deductibles, copayments, and coinsurance. In most states, Medicare standardizes these plans and identifies them with letters such as A, B, D, G, K, L, M, and N. While insurance companies may charge different premiums, the benefits remain standardized for each plan letter. This guide explains Medicare Supplement Plans A Through N, including what each plan covers and how to compare your options.
What Are Medicare Supplement Plans A Through N?
Medicare Supplement Plans work alongside Original Medicare Parts A and B. Medicare pays its share of approved healthcare costs first. Your Medicare Supplement Plan may then help cover certain remaining costs. Medicare Supplement Plans do not include prescription drug coverage. Beneficiaries who want prescription drug coverage typically enroll in a separate Medicare Part D plan. It is also important to understand that Medicare Supplement Plans differ from Medicare Advantage plans. In most cases, you cannot have both types of coverage at the same time. For a better understanding of Original Medicare, see our guide to Medicare Parts A and B.
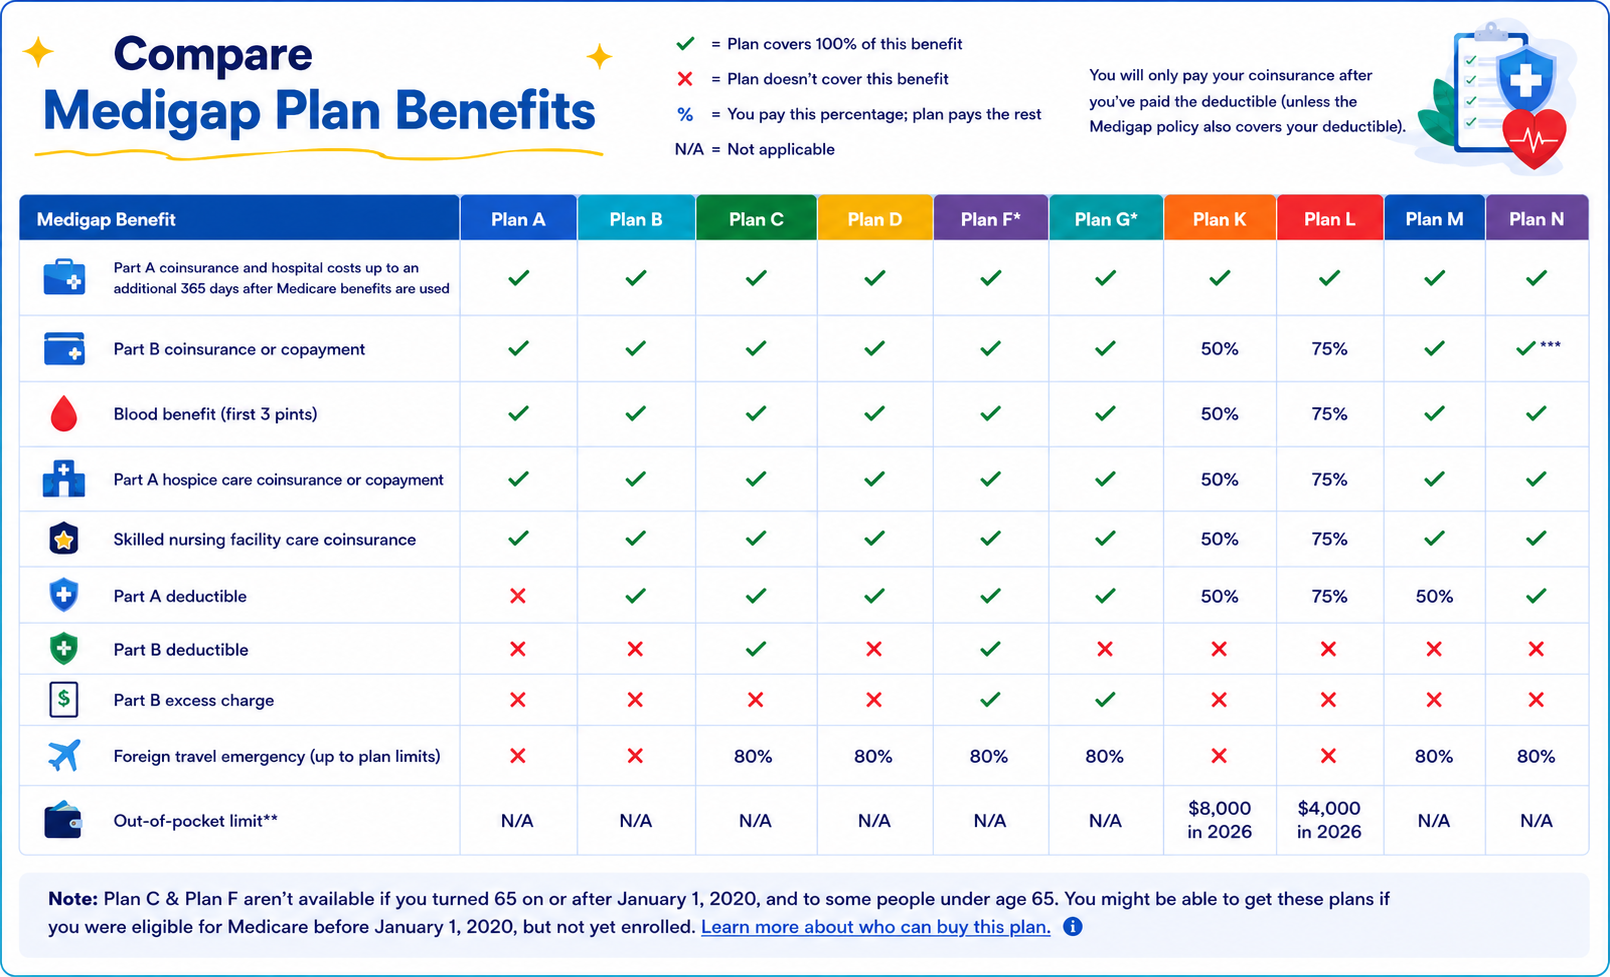
Medicare Supplement Plans A Through N Coverage Overview
Understanding the coverage differences among Medicare Supplement Plans A Through N can help beneficiaries compare benefits, premiums, and out-of-pocket costs before choosing a plan.
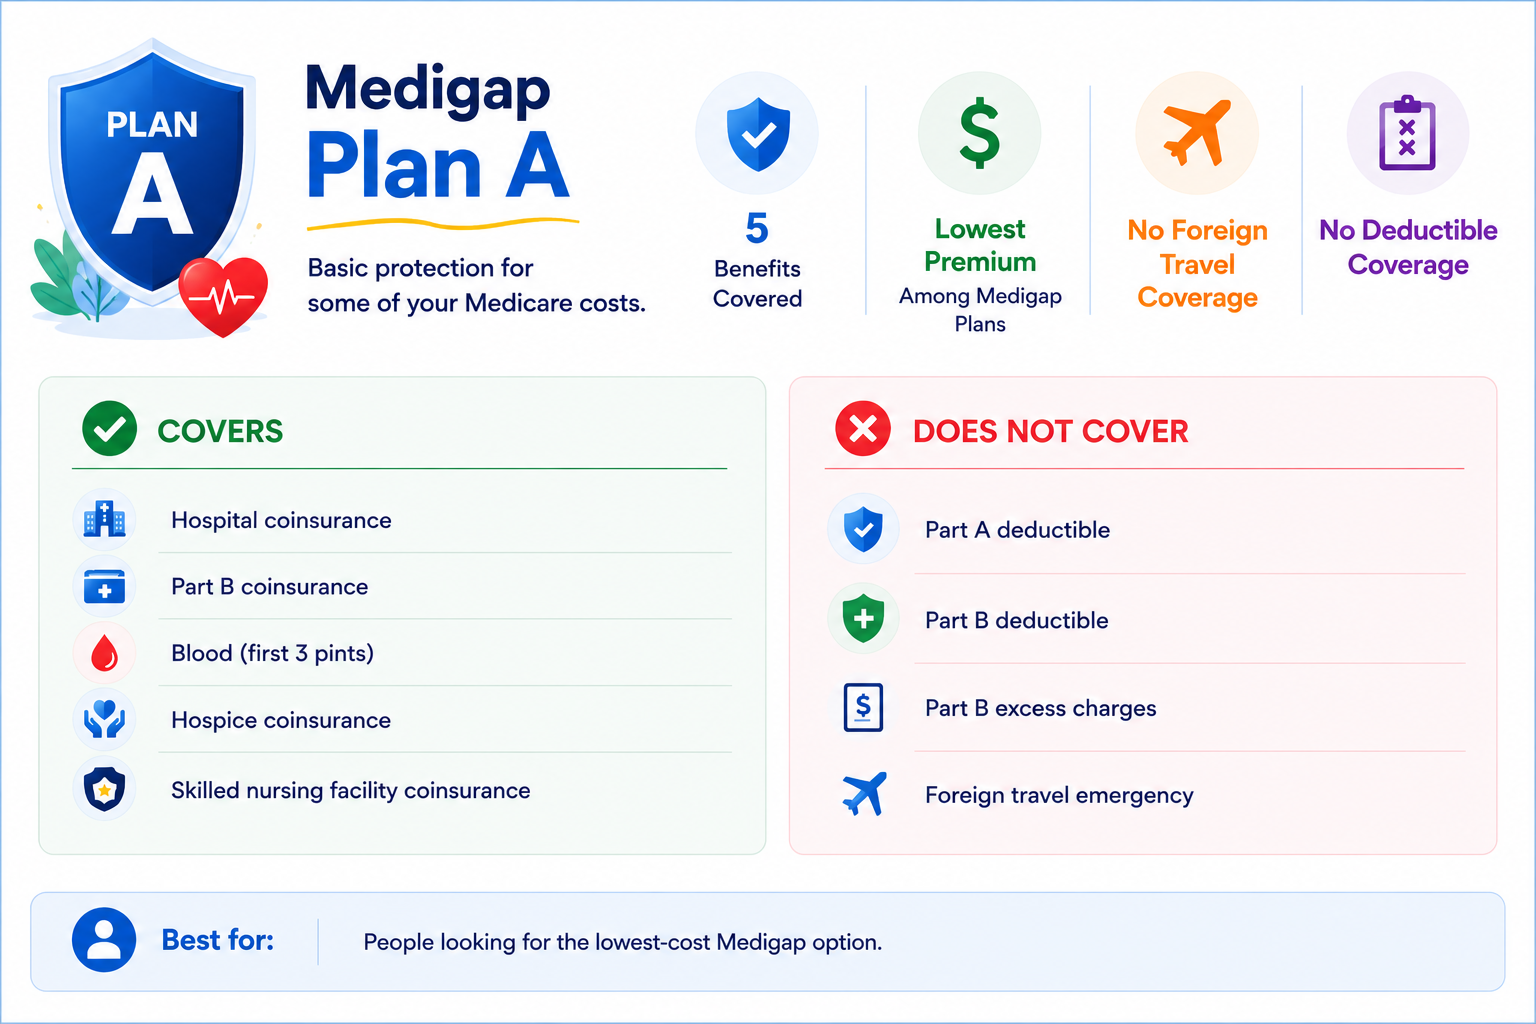
Plan A
Plan A provides the most basic coverage among Medicare Supplement Plans. It includes the core benefits that every Medicare Supplement Plan must offer. These benefits include Medicare Part A coinsurance, Medicare Part B coinsurance, blood transfusions, and hospice care coinsurance. Plan A often has lower premiums than other Medicare Supplement Plans. However, it also provides less comprehensive coverage.
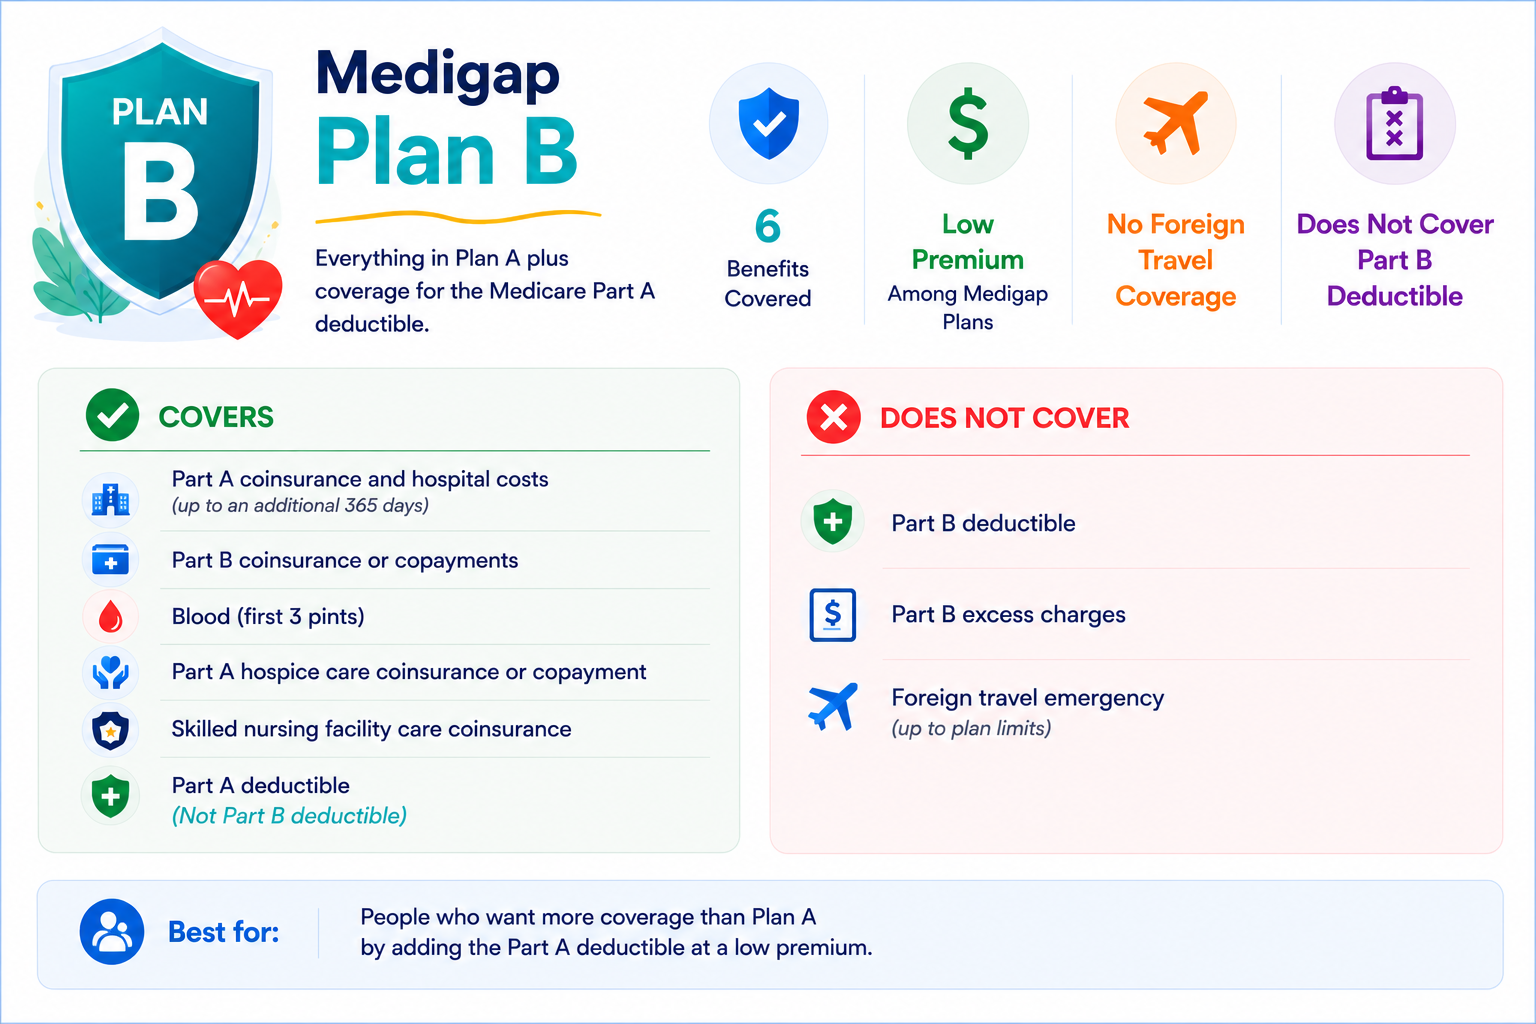
Plan B
Plan B includes all of the benefits offered by Plan A. It also adds coverage for the Medicare Part A deductible. This additional coverage can help reduce out-of-pocket costs associated with hospital stays.
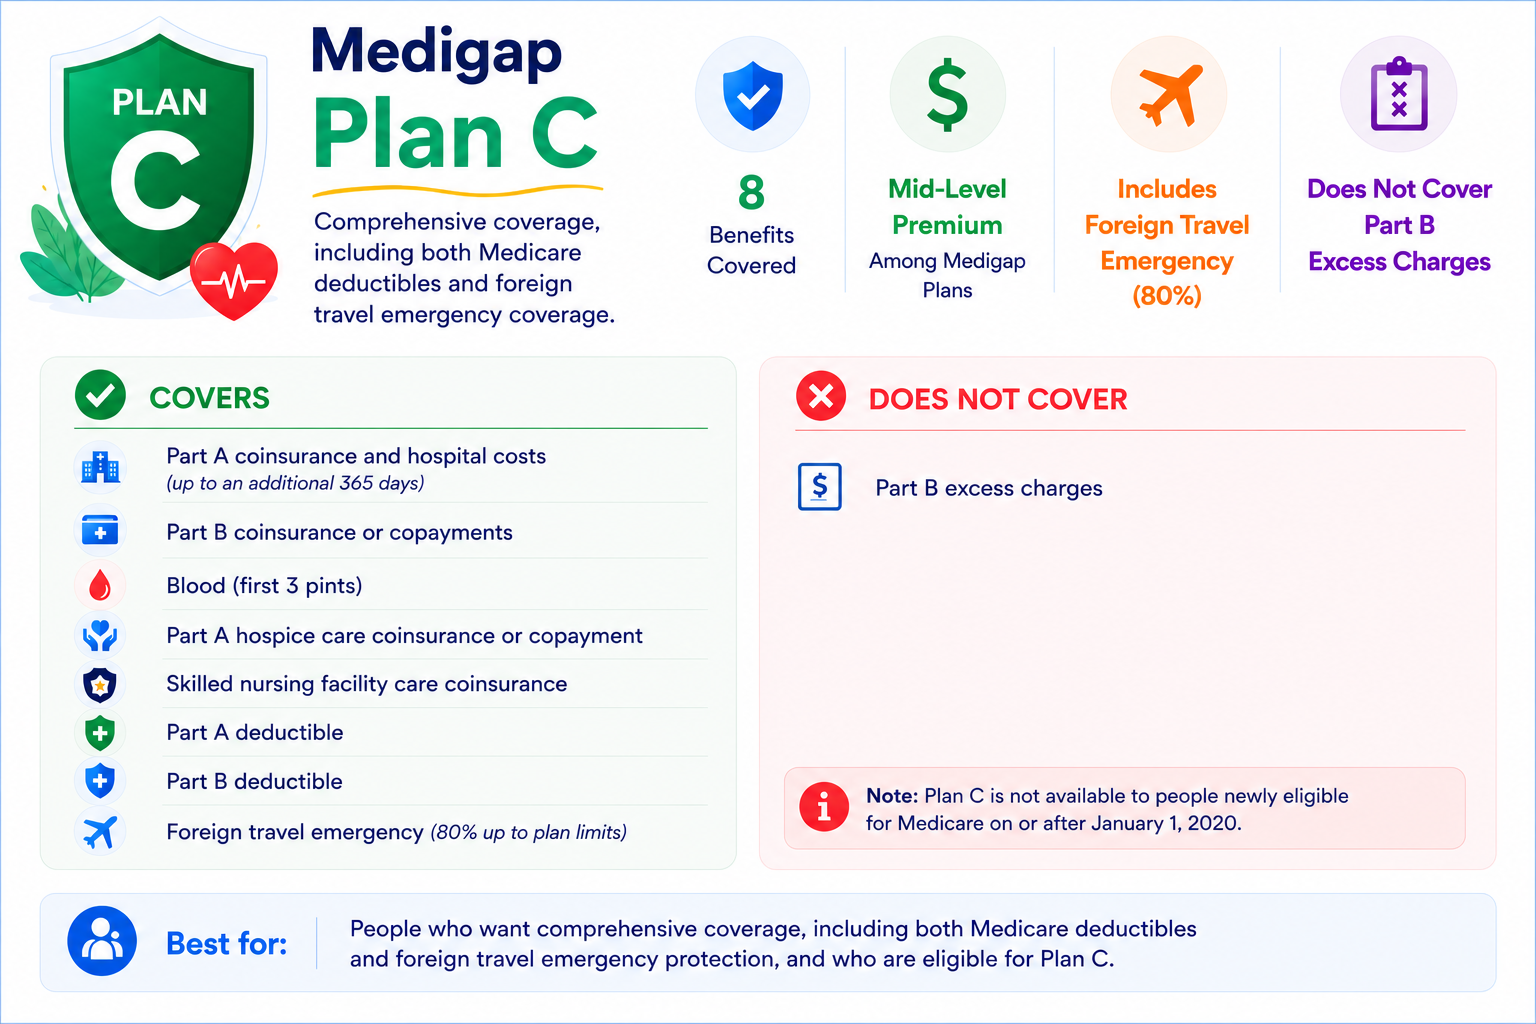
Plan C
Plan C once offered comprehensive coverage, including both the Medicare Part A deductible and the Medicare Part B deductible. However, Medicare no longer offers Plan C to people who became eligible for Medicare on or after January 1, 2020. If you became eligible for Medicare before that date, you may still be able to purchase Plan C if insurance companies offer it in your area.
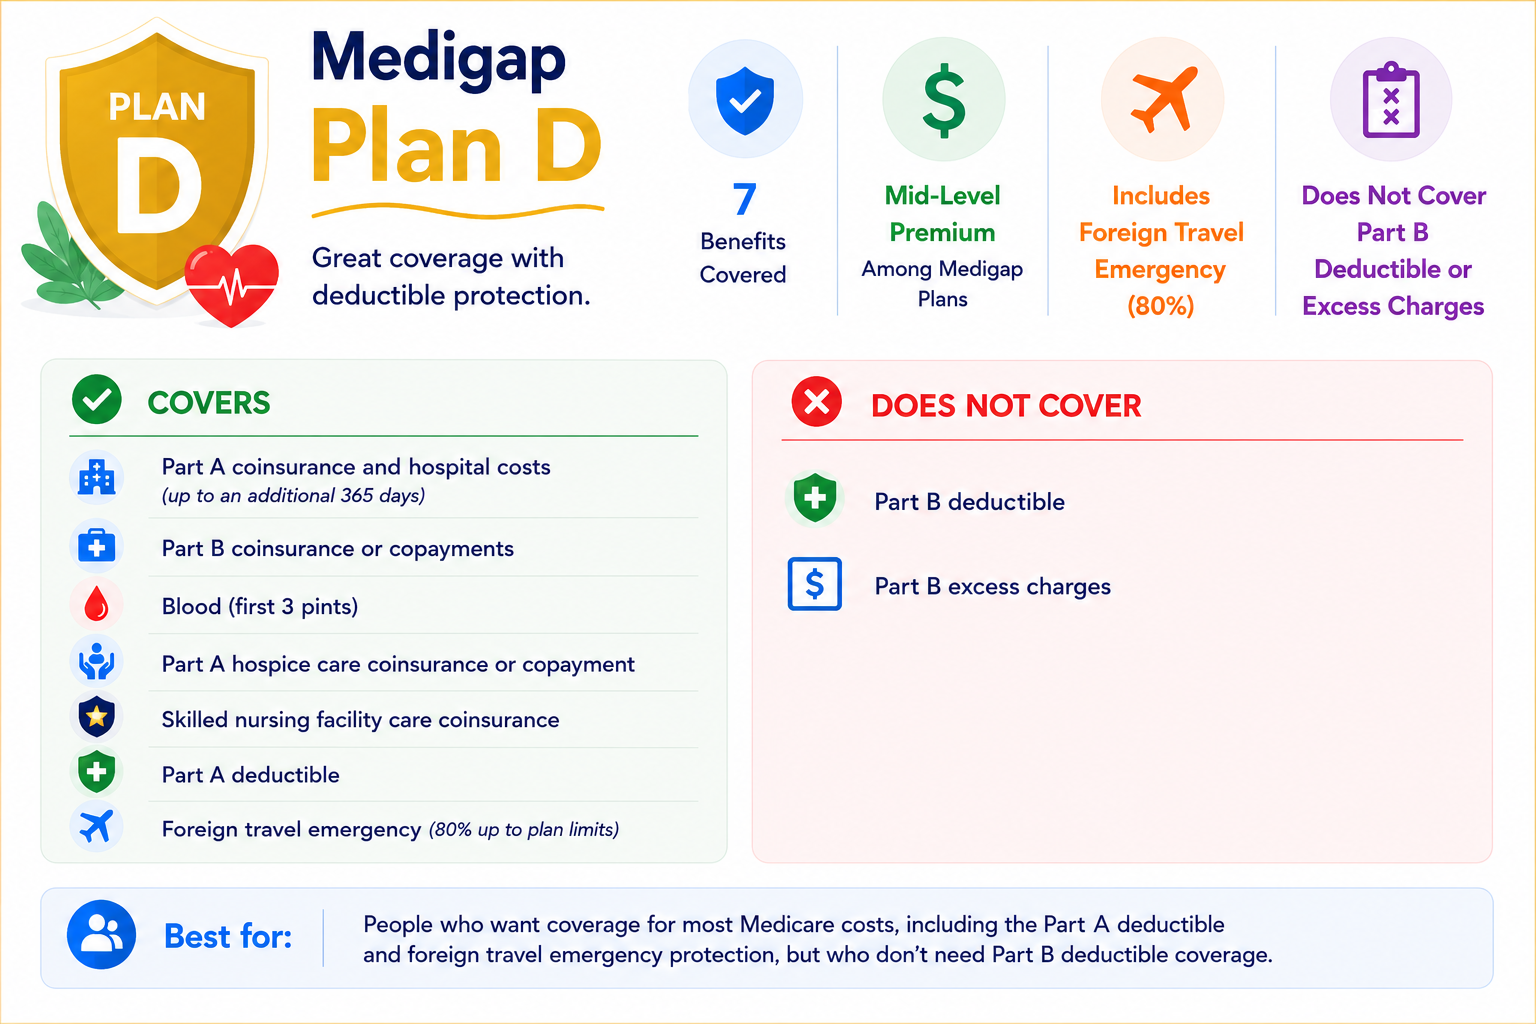
Plan D
Plan D includes many of the same benefits as Plan C. However, it does not cover the Medicare Part B deductible. Plan D also includes coverage for skilled nursing facility coinsurance and foreign travel emergency benefits.
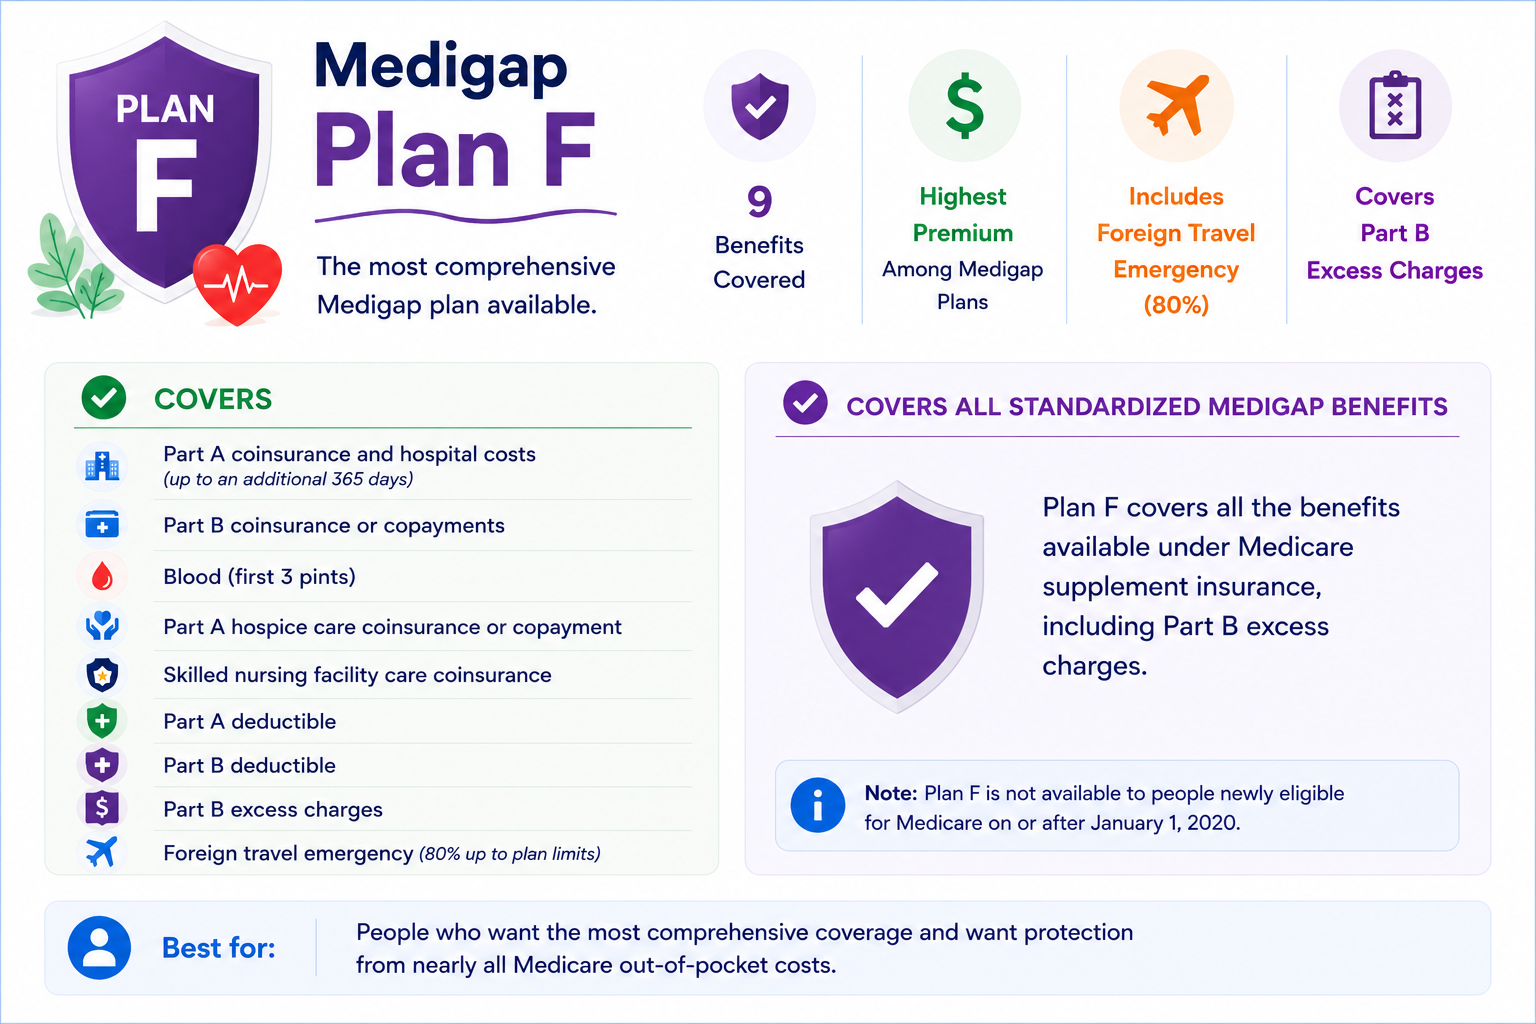
Plan F
Many beneficiaries consider Plan F the most comprehensive Medicare Supplement Plan because it covers nearly all Medicare-approved out-of-pocket costs. However, Medicare generally limits Plan F to beneficiaries who became eligible for Medicare before January 1, 2020. Many people who already have Plan F continue to keep it because of its broad coverage.
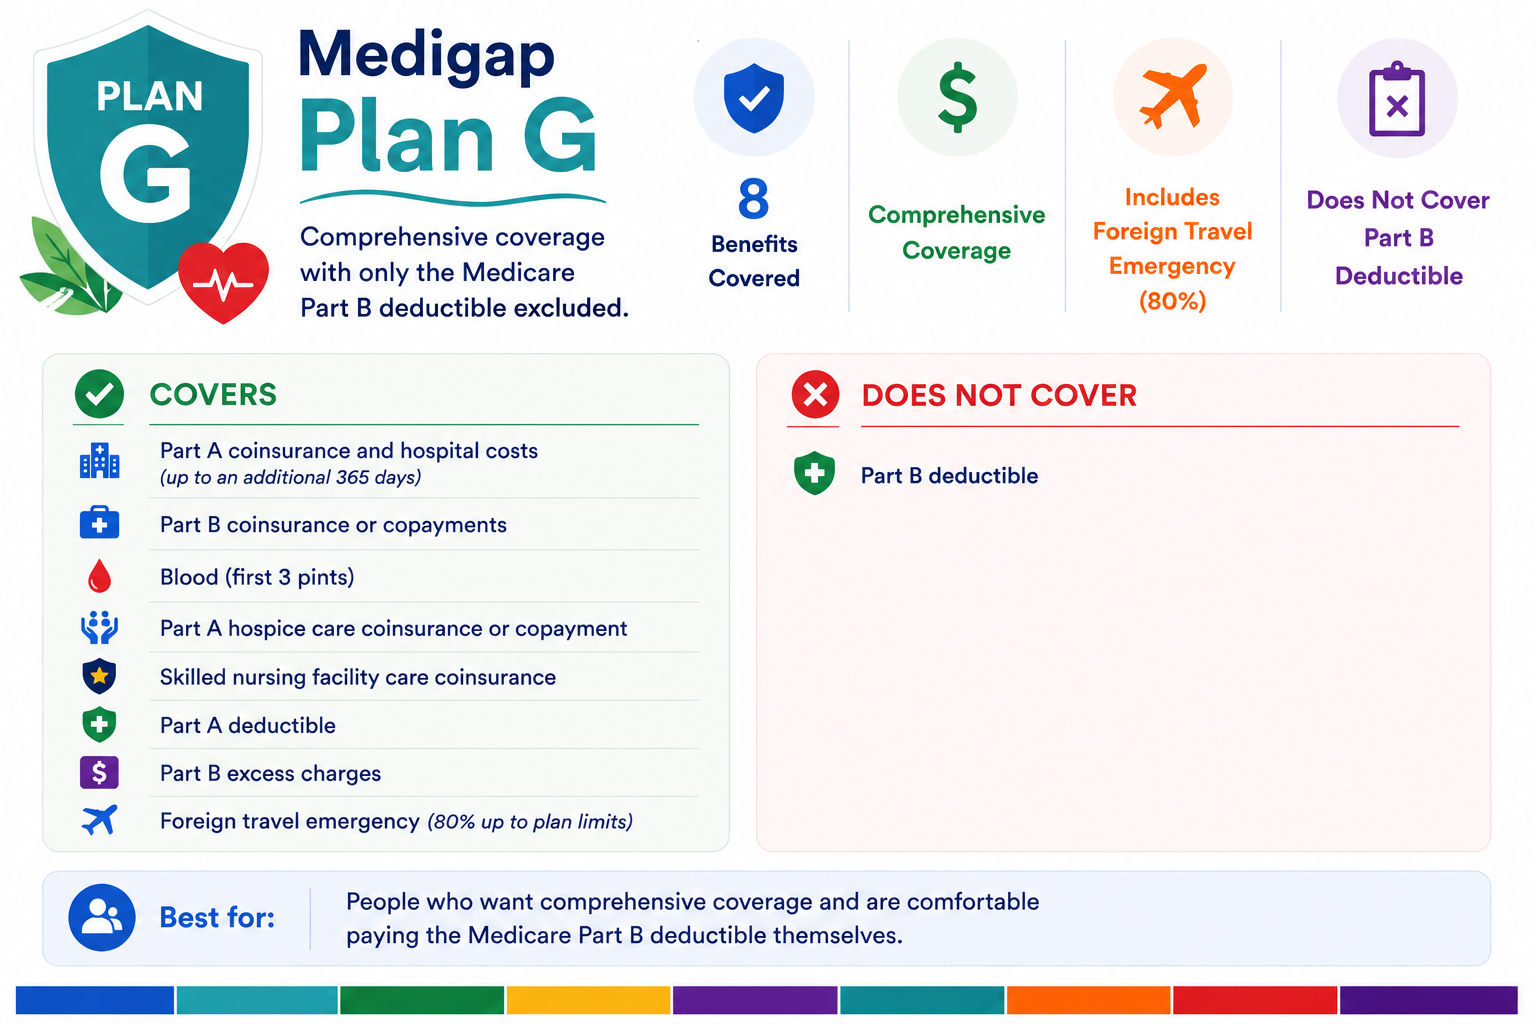
Why Plan G Is So Popular
Plan G has become one of the most popular Medicare Supplement Plans available today. It offers coverage that closely mirrors Plan F. The biggest difference is that Plan G does not cover the Medicare Part B deductible. After you pay the Part B deductible, Plan G typically covers most remaining Medicare-approved costs. Many beneficiaries choose Plan G because it combines strong coverage with availability for newer Medicare enrollees.
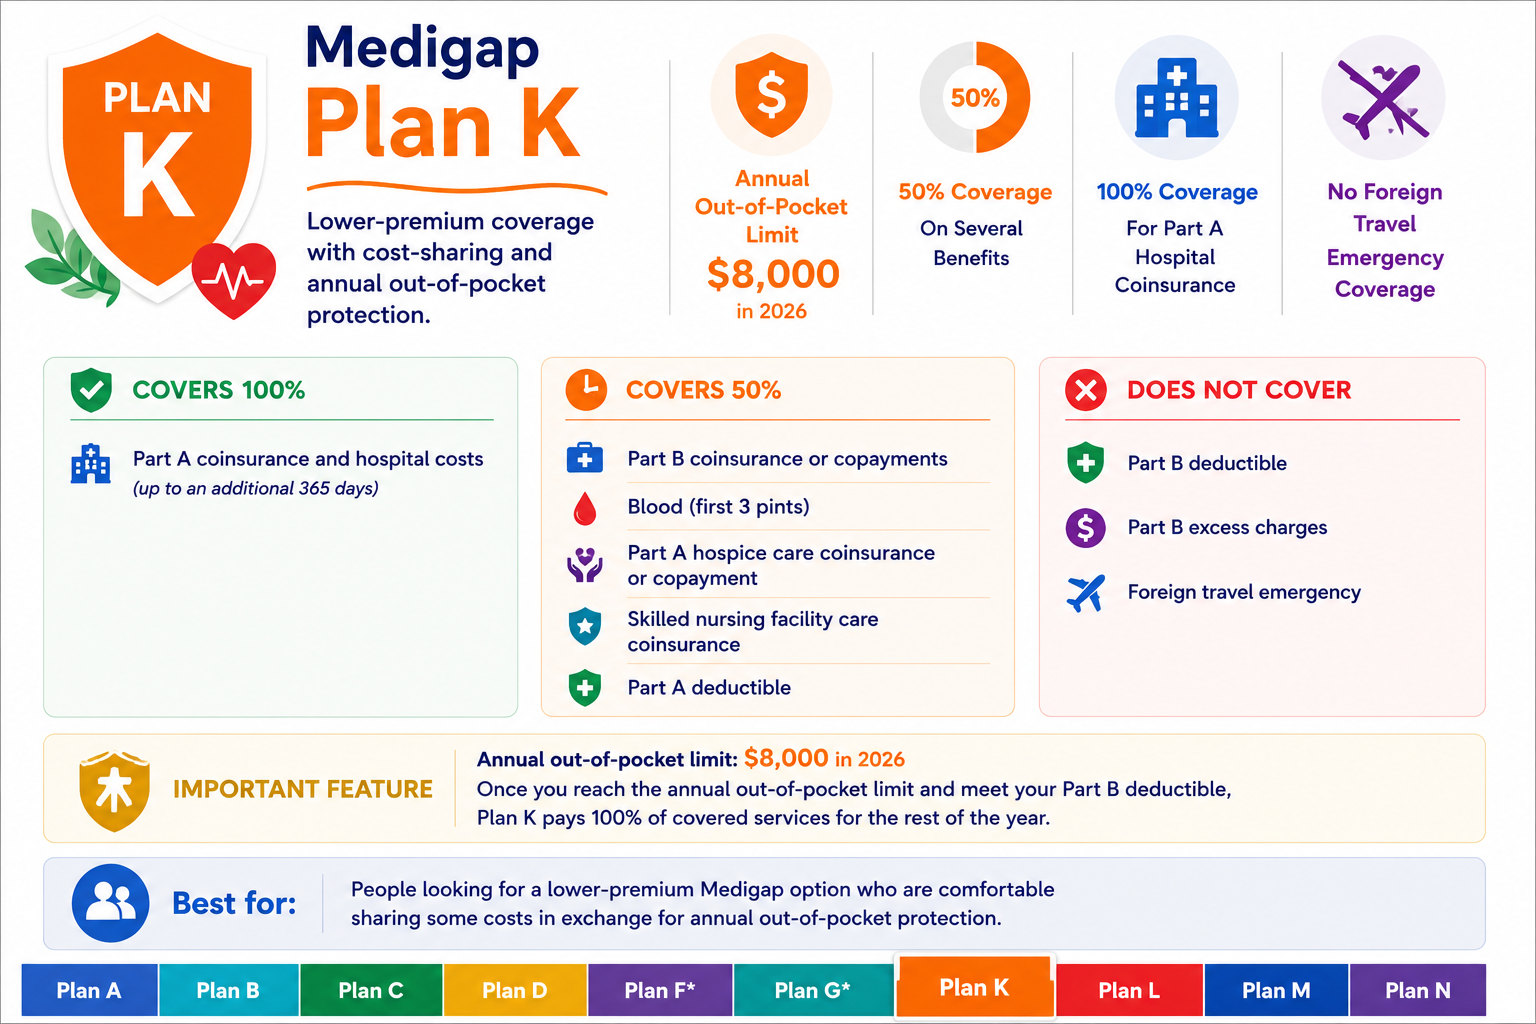
Plan K
Plan K offers lower monthly premiums in exchange for greater cost-sharing. Instead of paying 100% of certain costs, Plan K generally covers a percentage of covered expenses until you reach the plan’s annual out-of-pocket limit. After reaching that limit, the plan pays 100% of covered services for the remainder of the year.
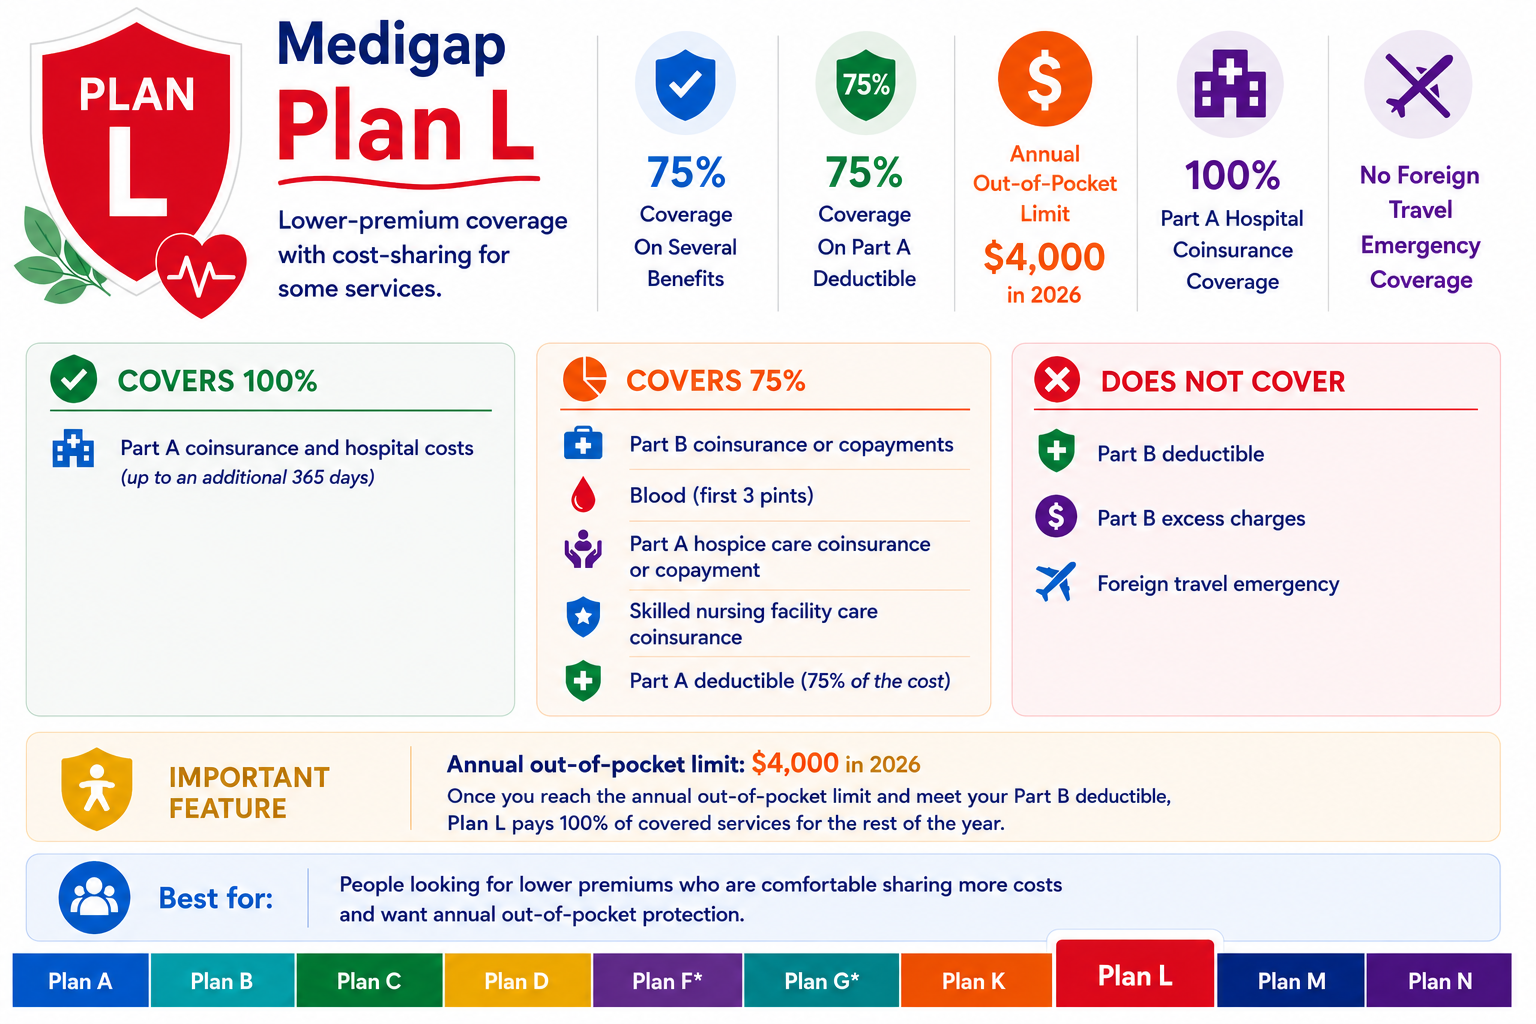
Plan L
Plan L works similarly to Plan K. However, it generally covers a higher percentage of costs before you reach the annual out-of-pocket limit. Like Plan K, Plan L provides protection against unexpectedly high medical expenses.
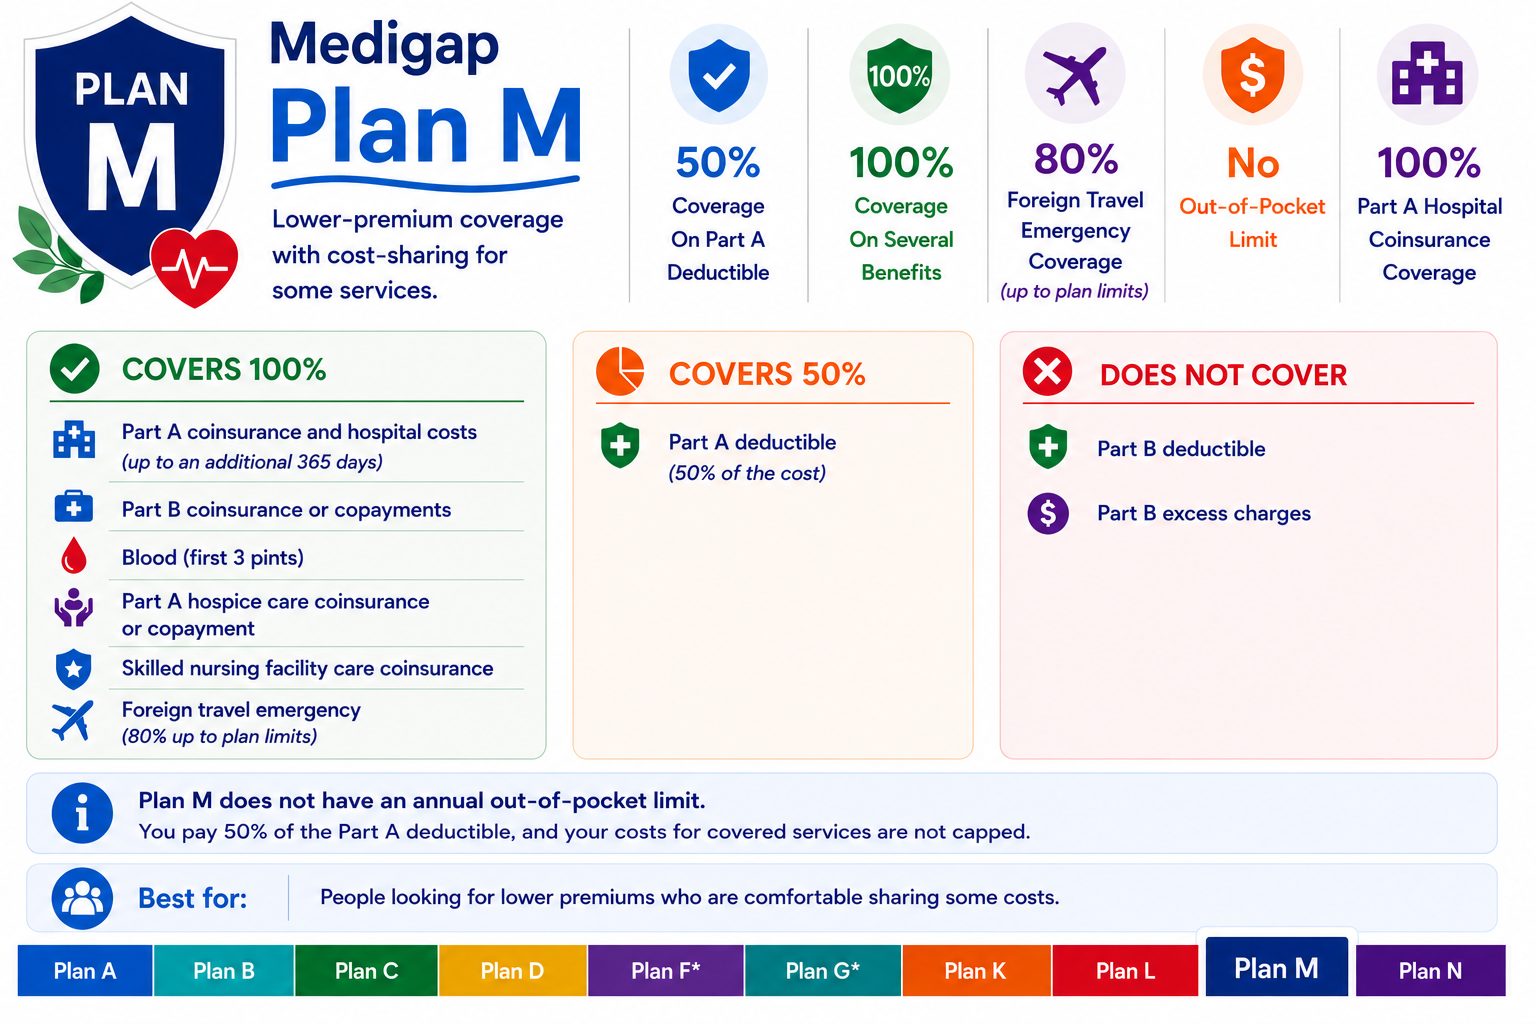
Plan M
Plan M balances monthly premium costs and coverage. One unique feature of Plan M is that it covers only part of the Medicare Part A deductible while still offering many standard Medigap benefits. Beneficiaries who want lower premiums and feel comfortable sharing some healthcare costs may find Plan M appealing.
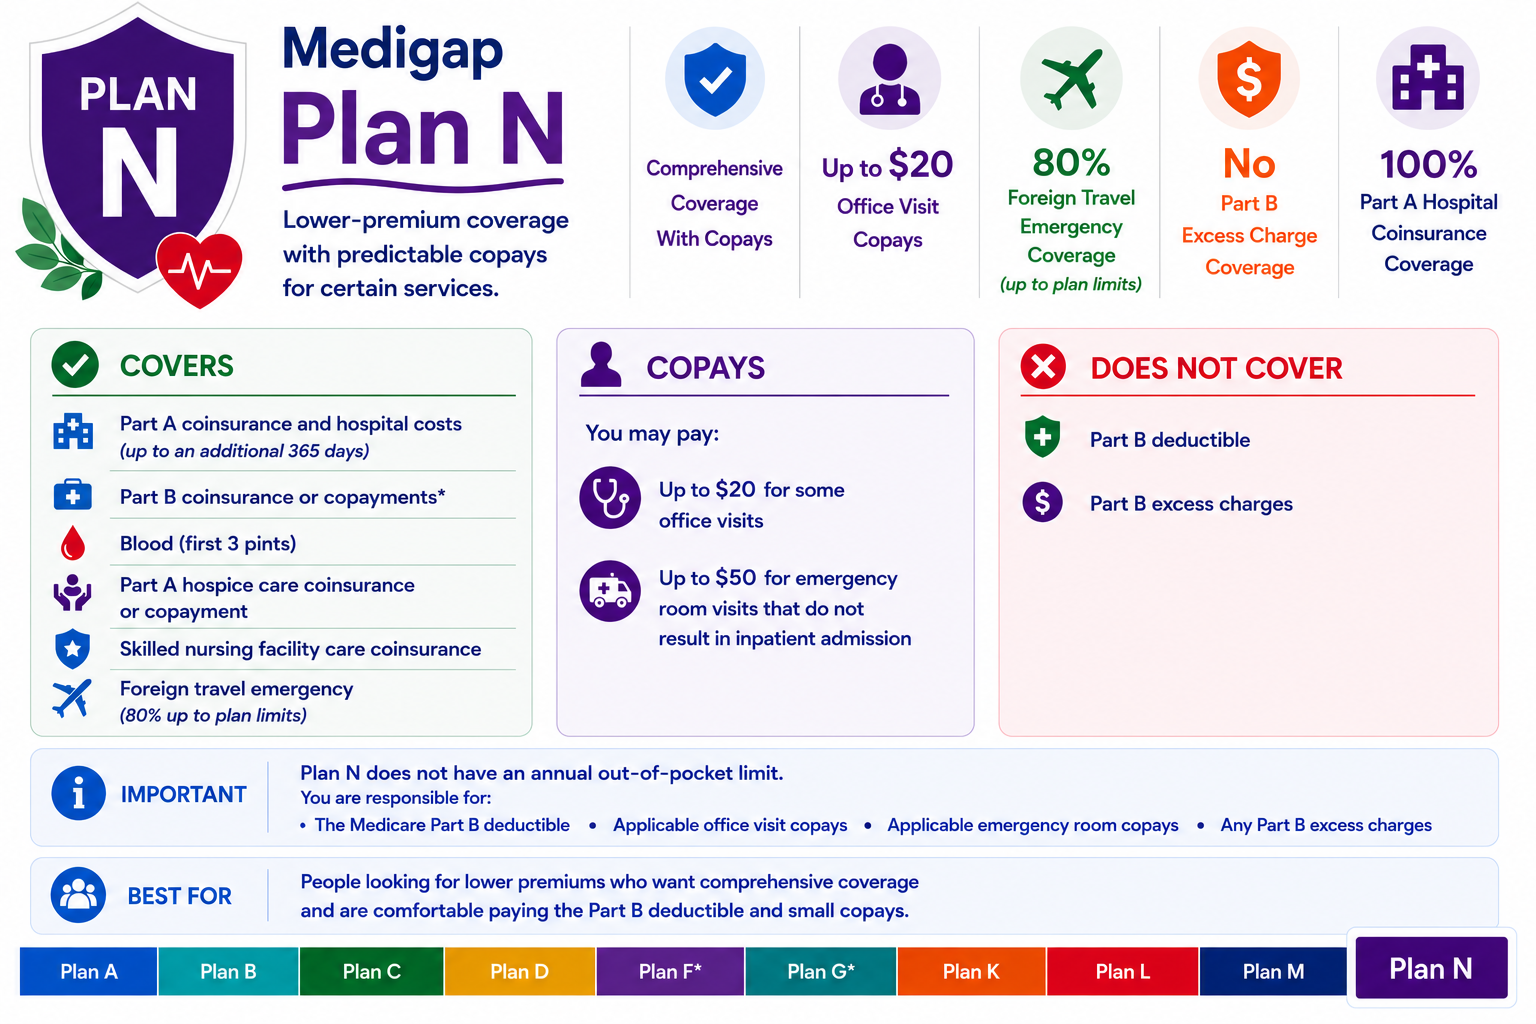
Plan N
Plan N remains one of the most popular Medicare Supplement Plans available today. It generally offers lower premiums than Plan G in exchange for some cost-sharing. Beneficiaries may pay copayments for certain office visits and emergency room visits. Plan N also does not cover Medicare Part B excess charges. Many healthy Medicare beneficiaries choose Plan N because it can provide a balance between affordability and comprehensive coverage.
Comparing Medicare Supplement Plans A Through N
When comparing Medicare Supplement Plans A Through N, it is important to evaluate premiums, coverage levels, and potential out-of-pocket costs. Each plan offers a different balance between monthly premiums and out-of-pocket expenses. Some plans provide more comprehensive coverage, while others trade lower premiums for greater cost-sharing.
Which Medicare Supplement Plans A Through N Are Best?
No single Medicare Supplement Plan works best for everyone. The right plan depends on your budget, healthcare needs, travel habits, and comfort level with out-of-pocket costs. Some beneficiaries prefer the comprehensive coverage offered by Plan G. Others choose Plan N because of its lower premiums. Individuals who remain eligible for Plan F may decide to keep that coverage because of its broad benefits.
Federal Medicare rules standardize benefits for each lettered plan, but insurance companies set their own premiums. Because of this, comparing both coverage and pricing is important when evaluating Medicare Supplement Plans. You may also want to compare Medicare Supplement Plans with Medicare Advantage plans before making a final decision.
How a Local Medicare Broker Can Help
With so many Medicare Supplement Plans available, comparing options on your own can be challenging. A local Medicare broker can help you understand the differences between Plans A through N and explain how each option may fit your healthcare needs and budget. Because plan availability and pricing vary by location, a local broker can review the Medicare Supplement Plans available in your area and help you compare premiums from multiple insurance companies. A broker can also explain enrollment rules, underwriting requirements, and important deadlines that may affect your choices.
Most importantly, a local Medicare broker can provide personalized guidance. While Medicare standardizes the benefits for each plan letter, choosing the right plan often comes down to understanding your healthcare needs, financial goals, and long-term expectations.
Final Thoughts on Medicare Supplement Plans A Through N
Medicare Supplement Plans provide valuable protection against many of the out-of-pocket costs associated with Original Medicare. While the lettered plans may seem confusing at first, understanding the differences between Plans A through N can make choosing coverage much easier. Understanding Medicare Supplement Plans A Through N can help you make a more informed decision about your Medicare coverage. Whether you are new to Medicare or considering a change in coverage, taking time to understand your options can help you make a more confident decision about your healthcare future.
Get 1-on-1 AssistanceClick Here
Learn More About Medicare
You may also find these Medicare guides helpful:
Medigap Frequently Asked Questions
+ What do the Medicare Supplement Plan letters mean?
+ Which Medicare Supplement Plan offers the most coverage?
+ Why is Plan G so popular?
+ What is the difference between Plan G and Plan N?
+ Do Medicare Supplement Plans cover prescription drugs?
+ Can I have a Medicare Supplement Plan and a Medicare Advantage Plan?
Follow us on:
IMPORTANT NOTE: This information is for educational purposes only and is not a complete description of benefits. This scenario is a hypothetical example based on common real-life situations and does not represent any specific individual. Benefits, premiums, and plan availability may vary by location and plan provider.. For more information, visit Medicare.gov or speak with a licensed insurance professionals.